How to Earn with Insurance Affiliate Programs in 2026
Learning how to earn with insurance affiliate programs is one of the more rewarding routes in affiliate marketing, because insurers pay for leads as well as for sales. A reader who completes a car insurance quote form can earn you a commission even if they never buy a policy. A reader who buys a life insurance policy can earn you a far larger commission, often 50 to 150 US dollars or more. The trade off is trust. Insurance is a money topic, so readers and search engines expect careful, honest content, and regulators expect clear disclosure.
This guide shows you how to start in insurance affiliate marketing the honest way: pick one insurance niche, compare programs on the numbers that matter, apply to programs you can actually join, and build useful content before you expect income. It is not financial advice, and it does not promise income.
This guide is for beginners who already write about money, freelancing, small business, travel, or family life. You will learn how insurance affiliate programs work, which niches pay best, which programs to shortlist, how to promote them without misleading readers, and what a realistic first year looks like.
Disclosure: this article discusses affiliate links. If you request a quote or buy a policy through a link in this article, EarnQuill may earn a commission at no extra cost to you. The information in this article is for education only and is not personal financial advice. Read our full affiliate disclosure for details.
In this guide
- How insurance affiliate programs work
- Cost per lead vs cost per sale
- Insurance sub-niches you can start with
- Programs compared
- Step 1: Pick one insurance niche
- Step 2: Compare programs on six checks
- Step 3: Apply and set up tracking and payouts
- Step 4: Publish the three content types that convert
- Step 5: Track, update and grow
- Worked example
- What it costs and what to expect
- Common mistakes
- Risks and scams to watch for
- Frequently asked questions
How insurance affiliate programs work
An insurance affiliate program is a partnership between an insurer or an insurance marketplace and a publisher. You place a tracked link on your site. When a reader clicks it and completes a qualifying action, you earn a commission. The qualifying action is usually a completed quote form or a paid policy.
Most insurance brands run their programs through a large affiliate network such as CJ Affiliate or Awin, rather than on their own site. You join the network, find the brand inside it, and apply. Once you are approved, you get a tracking link and access to banners and reporting. The network tracks clicks, leads, and sales, and it pays you, usually monthly, once your balance passes a minimum threshold.
Insurance is different from most affiliate niches in two ways. First, the customer value is high. A car insurance customer may stay with one insurer for three to seven years, so insurers can afford to pay well for a new customer. Second, many programs pay per lead. You do not need to sell a policy. You only need to send a reader who completes a quote form. That lowers the bar for earning your first commission, but it also means lead quality matters. Networks check that your leads are real people who asked for a quote, and they can reverse commissions for fake or low quality leads.
You do not need to be an insurance agent to promote these programs. You do need to be honest about what you are doing. You are recommending a quote tool or a comparison service, not giving personal insurance advice. Never tell a reader which cover amount to choose, and never promise that a policy will be approved or that a claim will be paid.
Cost per lead vs cost per sale
Insurance programs pay in two main ways. Cost per lead, often shortened to CPL, pays you when a reader completes a quote form. Cost per acquisition, often shortened to CPA, pays you only when a reader buys and pays for a policy. Some programs mix the two. The table below compares them.
| Feature | Cost per lead (CPL) | Cost per acquisition (CPA) |
|---|---|---|
| Trigger | Reader completes a quote form | Reader buys and pays for a policy |
| Typical payout | 3 to 40 US dollars per lead | 25 to 300 US dollars per sale |
| Conversion difficulty | Low, the form is free | High, the reader must pay |
| Best for | Beginners and high traffic sites | Review and comparison content |
| Risk of reversal | Low, but fake leads are rejected | Moderate, cancelled policies can be reversed |
| Examples | Liberty Mutual auto quotes, Hiscox business quotes | Policygenius life insurance, Lemonade renters policies |
CPL suits beginners because the reader does not need to spend money. A car insurance quote takes a few minutes and costs the reader nothing, so more people complete it. CPA pays far more per action, but far fewer readers complete a purchase, and the sale can take weeks. Life insurance is the clearest example. A reader may research for a month before they buy, and the commission can be 100 to 300 US dollars, because the first year premium is large.
Choose your model to match your content. If you write broad guides that attract people early in their research, CPL programs will earn first. If you write detailed comparisons for readers who are ready to buy, CPA programs will pay more per conversion. Most successful insurance affiliates run both, with CPL programs on broad pages and CPA programs on buying guides.
Insurance sub-niches you can start with
Insurance is too broad to cover as one topic. A new site that tries to cover car, life, health, pet, and business insurance at once will struggle to build trust or rank. Pick one niche and own it first. These are the five most practical starting points.
Auto insurance has the highest volume. Car insurance is legally required in most places, so readers are not deciding whether they need it. They are deciding where to buy it. Payouts are usually 10 to 20 US dollars per completed quote. The audience is huge, but so is the competition.
Life insurance has the highest payouts. A term life policy can pay 50 to 150 US dollars per sale, and a whole life policy can pay far more, because commissions are often a percentage of the first year premium. The sales cycle is slow, often 30 to 60 days, and readers need a lot of trust before they buy. This niche suits personal finance and family blogs.
Home and renters insurance sits in the middle. Payouts are usually 10 to 25 US dollars per lead or 25 to 75 US dollars per sale. The audience is clear: new homeowners, new renters, and people moving house. It pairs well with real estate and home content.
Pet insurance is one of the fastest growing niches. Vet bills can run into thousands of dollars, so pet owners look for cover. Payouts are often 20 to 35 US dollars per lead or 50 US dollars or more per sale. It suits pet blogs and social media creators.
Business and commercial insurance pays well and has less competition from big publishers. Freelancers and small business owners need liability cover, professional indemnity, and workers compensation. Payouts are often 25 to 50 US dollars per quote. If you already write about freelancing or small business, this is a natural fit. Read our guide to how to earn with finance affiliate programs for the wider money niche, and our freelance taxes for beginners guide if your audience is freelancers.
Programs compared
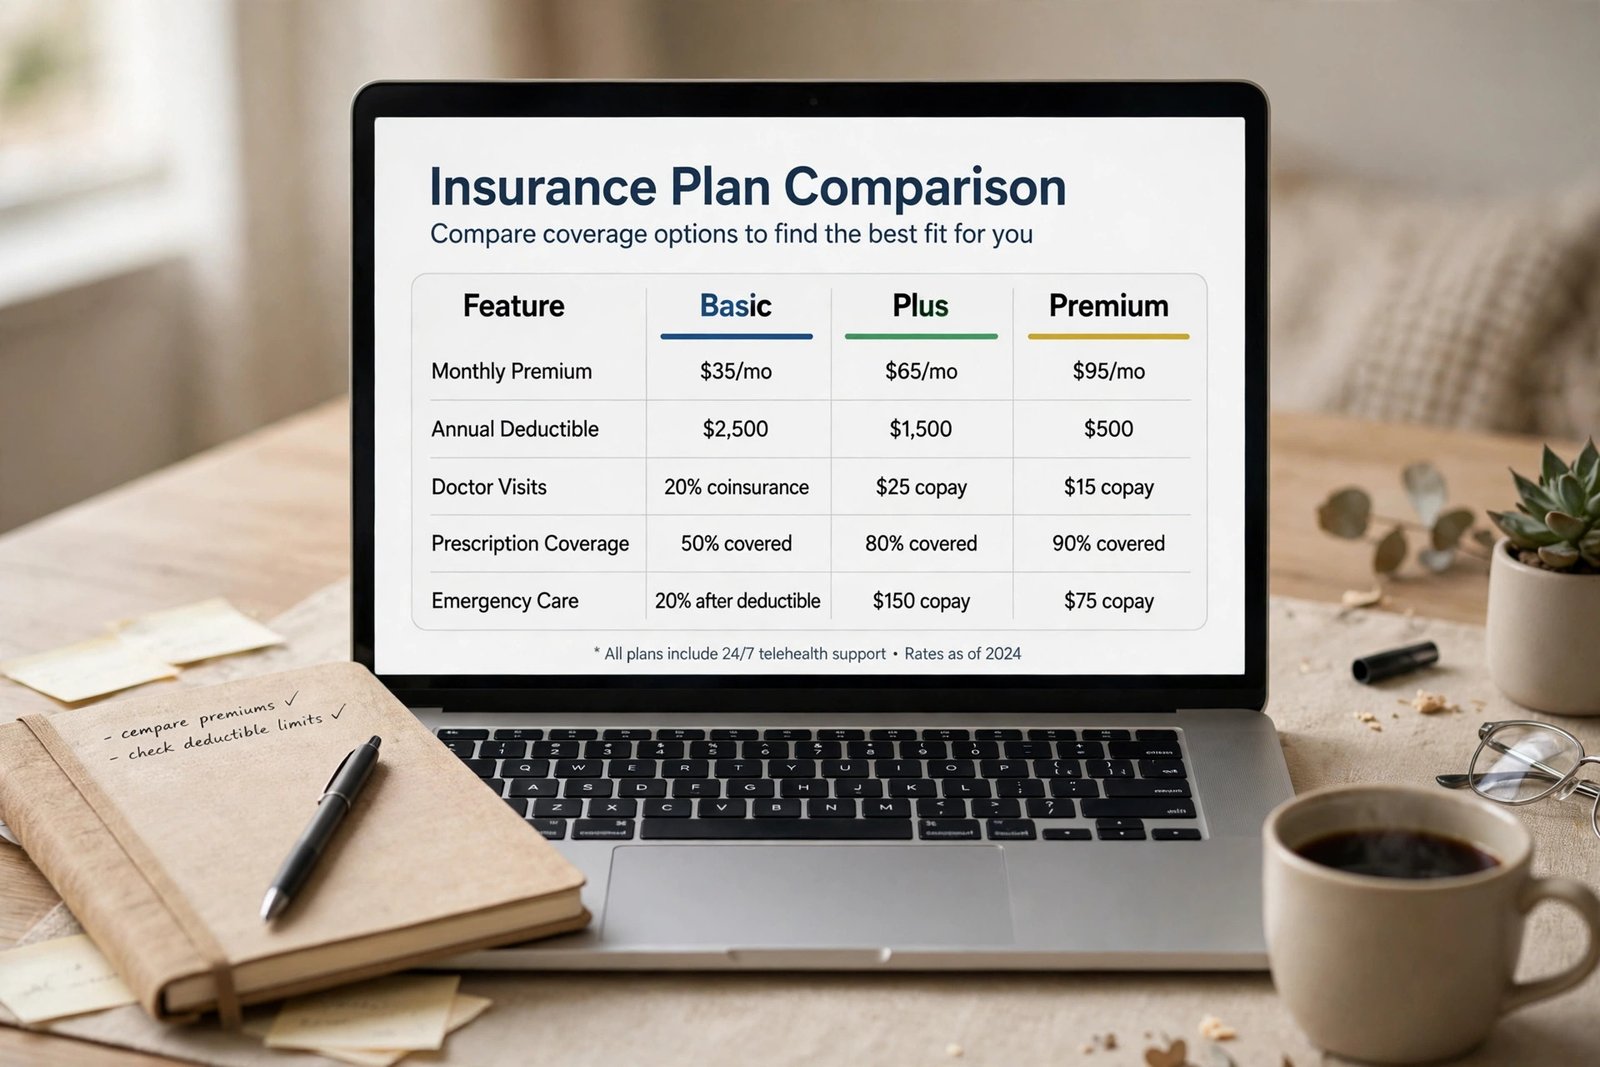
The table below compares eight programs that appear across the main affiliate guides. Figures are reported by affiliate guides and by the brands own pages, checked in November 2026. Always confirm the current terms in the network dashboard before you apply, because rates and cookie windows change.
| Program | Niche | Model | Typical payout | Cookie | Network |
|---|---|---|---|---|---|
| Liberty Mutual | Auto, home, renters | Per lead | 10 US dollars auto, 10 US dollars home, 3 US dollars renters | 30 days, guide reported | CJ Affiliate |
| Lemonade | Renters, home, pet, life | Per sale | About 25 US dollars per approved policy, guide reported | 30 days | Awin |
| Policygenius | Life, home, auto, disability | Per lead and per sale | Up to 75 to 120 US dollars per sale, guide reported | 60 days | CJ Affiliate |
| Ethos Life | Life insurance | Per lead | Not published on the official page | Not published | Impact |
| World Nomads | Travel insurance | Per sale | 10 percent of the policy premium | 60 days | Own program and CJ Affiliate |
| Hiscox | Small business | Per lead | 25 US dollars per completed quote | Not stated on the official page | CJ Affiliate |
| Embrace Pet Insurance | Pet insurance | Per lead | About 36 US dollars per completed lead, guide reported | 60 days | Affiliate networks |
| eHealth | Health and Medicare | Per sale | Up to 50 to 75 US dollars per sale, guide reported | 120 days | Affiliate networks |
Liberty Mutual is the most beginner friendly entry point, because it pays per completed quote and its terms are published on its own affiliate page. Its official page states 10 US dollars per lead for auto insurance quotes, 10 US dollars per lead for home insurance quotes, and 3 US dollars per lead for renters insurance quotes, and that sign-up runs through CJ Affiliate. Read the Liberty Mutual affiliate program page yourself before you apply. The CJ Affiliate site explains how the network works and how publishers get paid.
Policygenius suits comparison content, because one link can cover life, home, auto, and disability insurance. Ethos Life is worth noting for a different reason: its official affiliate page does not publish a fixed rate, and instead talks about competitive payouts and one to one support. Do not build content around a dollar figure for Ethos until you have seen the terms inside your own account. World Nomads is the natural choice if you write about travel, and it pairs with our guide to how to earn with travel affiliate programs.
Step 1: Pick one insurance niche
Start with the niche that matches your existing audience. If you write about family money, pick life insurance. If you write about cars or driving, pick auto insurance. If you write about freelancing, pick business insurance. If you write about travel, pick travel insurance.
Check three things before you commit. First, can you write at least 10 useful articles in this niche without repeating yourself? Second, do programs in this niche accept new publishers? Most auto and renters programs do. Some life insurance programs want to see finance content first. Third, does your audience live in a country the program covers? Most of these programs are US only, so a UK or Pakistani audience will not convert. Check the program terms for country limits before you write a single article.
Step 2: Compare programs on six checks
Do not choose a program on the headline payout alone. A 300 US dollar commission that never converts is worth less than a 10 US dollar lead that converts every day. Compare every program on these six checks.
First, the payout model. Per lead pays sooner and more often. Per sale pays more but needs more trust. Second, the cookie window. This is the number of days after a click during which you still earn the commission. A 30 day cookie is standard. A 60 or 120 day cookie matters for life and health insurance, where readers take weeks to decide. Third, the network. One network login can hold several programs, which makes reporting and payouts simpler. Fourth, the approval bar. Some programs accept any site with real content. Others want to see finance or insurance articles first. Fifth, the payout threshold and timing. Some networks pay from 10 US dollars, others from 50 or 100 US dollars, and most pay monthly. Sixth, the brand. A brand your readers already trust will convert far better than an unknown brand with a higher rate.
Write the six checks in a simple table for yourself before you apply. It takes 20 minutes and it stops you from chasing the biggest number.
Step 3: Apply and set up tracking and payouts
Apply to one network first, then to two or three programs inside it. CJ Affiliate hosts Liberty Mutual, Policygenius, and Hiscox. Impact hosts Ethos Life. Awin hosts Lemonade. A single network account keeps your reporting and payouts in one place.
Before you apply, make sure your site looks like a real publication. Programs check for an about page, a contact page, a privacy policy, and an affiliate disclosure page. They also check that you already publish useful content in a related topic. A site with five real articles will be approved far more often than an empty site with a single affiliate page.
Once you are approved, set up your payout details straight away, including your bank details and tax information. Networks will not pay you until this is complete. Then test your tracking link by clicking it yourself and completing a quote on a test basis only if the program allows it. Never submit fake quote forms to test a link. That is lead fraud, and it will get your account closed.
Add a clear disclosure near every affiliate link. A short line is enough: "We may earn a commission if you request a quote through this link." The FTC endorsement guides explain when and how to disclose a paid recommendation, and the same principle applies in most countries.
Step 4: Publish the three content types that convert
Insurance affiliate income comes from three content types. Publish all three, in this order.
First, comparison guides. "Best car insurance for new drivers" or "Term life vs whole life insurance" attract readers who are ready to choose. Compare three to five options on price, cover, exclusions, and claims process. Use a table. Link to the quote tool inside the comparison, not only at the end.
Second, explainer guides. "How much life insurance do I need" or "What does renters insurance cover" attract readers early in their research. These pages rank well and build trust. They rarely convert on their own, but they send readers to your comparison guides, so link between them.
Third, life event guides. People search for insurance when something changes: they buy a house, have a baby, get married, start a business, or get a new car. Write for the event, not for the product. "New parent checklist: money steps for the first year" will convert better than a generic life insurance page, because it reaches readers at the exact moment they need cover.
Do not write thin pages that only list programs. Google and readers both ignore them. Each article should answer a real question, explain the trade offs, and name the exclusions. If you are new to this, read how to start affiliate marketing and how to promote affiliate products before you publish your first insurance article.
Step 5: Track, update and grow
Check your network dashboard once a week. Look at clicks, quote starts, completed quotes, and sales. Most insurance links will never convert, and that is normal. Find the one or two pages that do convert, and write more content like them.
Update your program table every three months. Rates, cookie windows, and even whole programs change. A page that lists an old payout will lose reader trust and may breach the program terms. Keep a short note at the top of each article with the month you last checked the figures.
Once one niche earns steadily, add a second niche that shares the same audience. Auto insurance readers often need home insurance too. New parents who buy life insurance often need health cover as well. Cross link between your own guides so one reader can find the next relevant page. Track your results with the method in how to track affiliate earnings.
Worked example
Example only: these numbers are not typical results. They show the maths, so you can see how the model works.
Imagine you publish a comparison guide for car insurance quotes. It gets 1,000 visitors in a month. About 2 percent click your Liberty Mutual link. That is 20 clicks. About half of those readers complete a quote form. That is 10 completed quotes. At 10 US dollars per lead, that is 100 US dollars for the month from one article.
Now imagine the same article also links to a life insurance comparison. Of the same 1,000 visitors, 5 click through and 1 buys a term life policy. At 100 US dollars per sale, that is another 100 US dollars. Total for the month: 200 US dollars from one article.
Check the maths again. 1,000 visitors times 2 percent is 20 clicks. Half of 20 is 10 leads. 10 leads times 10 US dollars is 100 US dollars. 1 sale times 100 US dollars is 100 US dollars. 100 plus 100 is 200 US dollars.
This is an example, not a promise. A new article may get 50 visitors a month, not 1,000. Click rates are often below 2 percent. Most months will be slower than this example, and some months will earn nothing at all.
What it costs and what to expect
You can start insurance affiliate marketing for very little money. A domain and hosting cost roughly 50 to 100 US dollars a year. Joining affiliate networks and programs is free. Your main cost is time. Expect to spend 6 to 10 hours per article, including research, writing, and updating.
Income is slow at first. In the first three months, expect little or nothing, because new pages take time to rank and new sites take time to earn trust. In months four to six, a focused site with 10 to 20 good articles may see its first leads. In the first year, a realistic outcome for a part time publisher is a small number of leads per month, not a full time income. Results vary with traffic, audience, country, and how well your content matches what readers need.
The biggest cost is not money. It is the time you spend building trust in a niche where readers are rightly careful. Insurance is a YMYL topic, which means Google holds it to a higher quality standard. Thin or careless content will not rank, and it should not.
Common mistakes
- Promoting five insurance niches at once instead of owning one first.
- Choosing a program on the headline payout without checking the cookie window, the approval bar, or the country limits.
- Writing thin program lists with no real comparison, no exclusions, and no honest downsides.
- Giving specific insurance advice, such as telling a reader which cover amount to buy, without a licence.
- Hiding the affiliate disclosure at the bottom of the page, or leaving it out entirely.
- Using old payout figures without checking the current terms in the network dashboard.
- Buying traffic or submitting fake quote forms to test links, which is lead fraud and will close your account.
- Expecting income in the first month, then quitting before the content has time to rank.
Risks and scams to watch for
Insurance affiliate marketing has real risks. First, regulation. Insurance is regulated in almost every country, and the rules differ by state and by country. In the United States, some states require a producer licence for certain activities. In the United Kingdom, the Financial Conduct Authority regulates insurance promotion. In the European Union, the Insurance Distribution Directive applies. Check the rules where your readers live, and keep your content educational rather than advisory.
Second, lead quality. Networks reject leads that look fake, duplicated, or bought. Never buy leads, never offer a reward for completing a quote form, and never submit forms on behalf of someone else.
Third, fake quote sites. Some sites collect personal details through a quote form and then sell the data. Only promote brands and networks you have checked. If a program has no clear company details, no privacy policy, or no real contact information, do not promote it.
Fourth, policy cancellations. A CPA commission can be reversed if the reader cancels the policy during the cooling off period. Do not count income until the commission is confirmed and paid.
Fifth, misleading claims. Never promise that a reader will be approved, that a claim will be paid, or that a policy is the cheapest option. Compare honestly, name the exclusions, and let the reader decide.
Frequently asked questions
How much can you earn from insurance affiliate programs?
It varies widely. A single auto insurance lead can pay 10 US dollars, and a single life insurance sale can pay 100 US dollars or more. A new site may earn nothing for months, then a small number of leads per month. Income depends on traffic, audience quality, and how well your content matches what readers need. No honest guide can promise a figure.
Do you need a licence to promote insurance affiliate programs?
In most cases, no licence is needed to place an affiliate link and explain how a program works in general terms. You do need to be careful not to give personal insurance advice, recommend specific cover amounts, or guarantee approval, because those activities can require a licence in some countries and states. Check the rules where your readers live.
Which insurance affiliate program pays the most?
Life insurance programs usually pay the most per sale, because commissions are often a percentage of the first year premium. Auto and home insurance programs usually pay less per action but convert more often, because they pay per completed quote. The best program for you is the one that fits your audience and converts, not the one with the biggest headline number.
Do insurance affiliate programs pay per lead or per sale?
Both. Many auto, home, renters, and business programs pay per completed quote, which is cost per lead. Life, health, and travel programs often pay per completed sale, which is cost per acquisition. Some programs, such as Policygenius, use both models depending on the product.
Can I promote insurance affiliate programs without a website?
Yes, but it is harder. You can use YouTube, social media, or an email list, but most networks prefer to see a website with real content before they approve you. A website also lets your content rank in search and earn commissions for months after you publish it. Read affiliate marketing without a website for the options and their limits.
How long does it take to get paid?
Most networks pay monthly, once your balance passes a minimum threshold, often 10 to 100 US dollars depending on the network. Lead commissions are usually confirmed within days, while sale commissions can take 30 to 60 days, because the insurer waits to see that the policy stays active.
Conclusion
To earn with insurance affiliate programs, pick one niche that fits your audience, compare programs on payout model, cookie window, approval bar, and country limits, apply through a trusted network, and publish comparison guides, explainers, and life event guides that answer real questions. Disclose every affiliate link, keep your figures current, and never give personal insurance advice. Start small, track what converts, and let one niche earn before you add a second.
Next, read how to start affiliate marketing, how to earn with finance affiliate programs, and best affiliate programs for beginners. Browse all our guides in affiliate marketing.
Reader note: commission rates, cookie windows, payout thresholds, tax rules, and insurance regulation differ by country and change often. Figures in this article were checked against official program pages and affiliate guides in November 2026. Check the current terms before you apply, and check your local tax authority or a qualified accountant about declaring affiliate income. Earning results vary; nothing on this site is financial advice.